NRI Taxation & Cross-Border Compliance Services in Mumbai
RVG Consulting Private Limited offers practical solutions in NRI taxation, property transaction advisory, FEMA compliance, and cross-border compliance services in Mumbai, India. We assist Non-Resident Indians (NRIs), Persons of Indian Origin (PIOs), Overseas Citizens of India (OCIs), and returning NRIs in managing their Indian tax liabilities, asset transfers, and tax filings from abroad. Our main services include supporting clients with NRI income tax return filing, capital gains taxation, TDS compliance, and fund repatriation requirements. We also assist with DTAA relief, Foreign Tax Credit claims, FEMA and RBI compliance,, and income tax notice handling. Through expert guidance and end-to-end support, we help NRIs manage their Indian financial and tax responsibilities while ensuring compliance with applicable regulations.
Important Tax Law Update: The Income-tax Act, 2025 applies from 1 April 2026 for Tax Years beginning on or after that date. The Income-tax Act, 1961 continues to govern earlier tax years and related transitional proceedings.
Who We Help
Our NRI Taxation and cross-border compliance services are professionally developed for individuals, investors, and businesses having Indian income, investments, property or regulatory obligations while operating or living across borders.
- NRIs living overseas: Individuals with Indian tax or regulatory obligations and are residing in the UAE, USA, UK, Canada, Australia, Singapore, the Middle East, and other countries.
- NRIs who are selling property in India: Non-residents who are selling residential or commercial property in Mumbai or somewhere else in India and requiring support with capital gains, TDS under Section 393(2) of the Income-tax Act, 2025 (corresponding to Section 195 of the Income-tax Act, 1961 for earlier periods), Form 13 for earlier periods / Form 128 under the new Act, and repatriation.
- NRIs earning rental income: Non-residents who are earning rental income from Indian property and needs professional guidance with TDS, income tax returns, deductions, and tax compliance.
- NRIs transferring funds overseas: Individuals transferring eligible funds from NRO accounts or remitting proceeds from Indian investments or property transactions who require Form 145 / Form 146 under the Income-tax Act, 2025 (replacing Forms 15CA/15CB for remittances from 1 April 2026) and FEMA/RBI compliance support.
- Foreign investors with Indian tax or FEMA obligations: Individuals and entities having investments, assets, transactions, or financial interests in India that may involve Indian taxation, withholding tax, FEMA, or RBI requirements.
- Returning NRIs: Individuals relocating to India who require guidance on residential status, RNOR considerations, overseas assets, foreign income, bank-account reclassification, and related tax compliance.
- Businesses involved in cross-border transactions: Businesses and organizations requiring assistance with Indian withholding tax, cross-border payments, foreign exchange regulations, documentation, and applicable tax or regulatory compliance.
Core NRI Tax & Regulatory Services
NRI Income Tax Return (ITR) Filing
Applicability
NRIs with Indian-source income exceeding the basic exemption limit, capital gains, or taxable rental income.
Scope of Service
- Determination of residential status under Section 6 of the applicable Income-tax law.
- Computation of Indian-sourced income (rent, dividends, interest, capital gains).
- Form 26AS, AIS (Annual Information Statement), and TIS reconciliation.
- E-filing of relevant ITR forms (ITR-2 / ITR-3) and refund processing.
NRI Capital Gains Tax Advisory
Applicability
Sale or transfer of Indian immovable property, equity shares, mutual funds, or debt instruments.
Scope of Service
- Computation of Short-Term (STCG) and Long-Term Capital Gains (LTCG).
- Cost Inflation Indexation (CII) analysis for eligible assets.
- Evaluation of capital gains exemptions under Sections 82, 86, and 85 of the Income-tax Act, 2025 (corresponding broadly to Sections 54, 54F, and 54EC of the Income-tax Act, 1961).
Lower or Nil TDS Deduction Certificate (Form 13)
Applicability
Avoidance of excess TDS withholding when actual tax liability is lower.
Scope of Service
- Preparation and filing of Form 128 under Section 395(1) of the Income-tax Act, 2025 (corresponding to Form 13 under Section 197 of the Income-tax Act, 1961).
- Direct representation and response management with Assessing Officers (AO).
- Procurement of the Lower/Nil Tax Deduction Certificate under Section 395(1) of the Income-tax Act, 2025.
Fund Repatriation & Remittance Compliance
Applicability
Transferring funds from NRO accounts to overseas bank accounts or remitting proceeds from Indian investments or property transactions, subject to applicable RBI/FEMA rules.
Scope of Service
- Issuance of Chartered Accountant Certificate Form 146 under the Income-tax Act, 2025 (corresponding to Form 15CB under the Income-tax Act, 1961).
- Filing of Form 145 under the Income-tax Act, 2025 (corresponding to Form 15CA under the Income-tax Act, 1961).
- AD Bank (Authorized Dealer) coordination for smooth outward remittance.
Property Tax Services in Mumbai
Applicability
NRIs buying, renting, or selling commercial/residential real estate in Mumbai and across India.
Scope of Service
- TDS compliance under Section 393(2) of the Income-tax Act, 2025 (corresponding to Section 195 of the Income-tax Act, 1961 for earlier periods).
- Rental yield tax structuring and flat 30% standard deduction claims under Section 22(1)(a) of the Income-tax Act, 2025 (corresponding to Section 24(a) of the Income-tax Act, 1961).
- Capital gains optimization and repatriation of sale proceeds.
| Property Transaction Aspect | Applicable Tax / Regulatory Provision | Primary Compliance Requirement |
|---|---|---|
| Rental Income | Section 22(1)(a) / Section 393(2), where applicable | 30% standard deduction + TDS filing by tenant |
| Property Sale | Section 393(2) of the Income-tax Act, 2025 / Section 195 under the earlier Act | Buyer deducts applicable TDS; lower deduction certificate may be available under Section 395(1) |
| Repatriation | RBI / FEMA Guidelines | Form 145 & Form 146 under the new tax framework, where applicable |
Double Taxation Avoidance Agreement (DTAA) Relief
Applicability
NRIs subject to tax on the same income in India and their home country of residence.
Scope of Service
- Evaluating Article provisions (Interest, Dividends, Capital Gains, Royalties).
- Obtaining and validating Tax Residency Certificates (TRC) and Form 10F.
- Applying beneficial DTAA tax rates over domestic tax rates.
Foreign Tax Credit (FTC) Filing
Applicability
Claiming tax credits in the resident country for taxes paid in India (or vice versa).
Scope of Service
- Preparation and e-filing of Form 44 under the Income-tax Act, 2025 (corresponding to Form 67 under the earlier framework).
- Cross-border income alignment and documentation verification.
FEMA & RBI Regulatory Compliance
Applicability
Oversight of cross-border financial transactions, account operations, and foreign investments.
Scope of Service
- Management and conversion advisory for NRE, NRO, and FCNR(B) bank accounts.
- FEMA guidelines on real estate acquisitions and inheritance structuring.
- Reporting under Foreign Direct Investment (FDI) or Overseas Investment frameworks where applicable.
NRI TDS Compliance & Reconciliation
Applicability
Deduction, deposit, and reconciliation of tax withheld at source under Section 393(2) of the Income-tax Act, 2025 for payments to non-residents.
Scope of Service
- TAN registration for buyers acquiring property from NRIs.
- Quarterly TDS return filings (Form 144 under the new framework, corresponding to Form 27Q under the earlier framework).
- Issuance of Form 131 / applicable TDS certificates under the new framework.
Income Tax Notice Handling & Representation
Applicability
Mismatches in AIS/Form 26AS, non-filing communications, scrutiny notices, and reassessment proceedings.
Scope of Service
- Analysis of communications from the e-Filing portal.
- Drafting legal/factual submissions and submitting online responses.
- Reconciliation of high-value transaction queries (SFT data).
- For matters governed by the Income-tax Act 2025, scrutiny and reassessment references should be made to the corresponding provisions, including Sections 270 and 280, as applicable. References to Sections 143(2) and 148 relate to proceedings governed by the Income-tax Act, 1961.
Returning NRI Transition Planning
Applicability
NRIs transitioning back to resident status in India.
Scope of Service
- RNOR (Resident but Not Ordinarily Resident) status tax optimization (tax-exempt foreign income for up to 2–3 years).
- Reclassification of NRE/NRO accounts to Resident savings accounts.
- Structuring overseas assets, stock options (RSUs/ESOPs), and foreign pensions.
The NRI Service & Compliance Process
Status & Income Assessment
Initial Evaluation
We determine your tax residency status of the applicable Income-tax law and review all global and Indian income streams, property assets, and foreign taxes paid.
Regulatory Framework Mapping
DTAA & FEMA Strategy
We map applicable provisions across Income Tax, DTAA benefits, lower TDS provisions under Section 395(1) of the Income-tax Act, 2025 where applicable, and FEMA/RBI limits for your transactions.
Documentation & Certification
Form Preparation
Our team compiles statutory requirements, including Form 145/146 under the Income-tax Act, 2025, Tax Residency Certificates (TRC), Form 10F, and investment reports.
E-Filing & Portal Submissions
Authority Submission
We handle e-filings directly on the Income Tax Department and TRACES portals, verifying reconciliation against AIS/TIS data.
Frequently Asked Questions (NRI Tax Knowledge Base)
Does an NRI have to file an income tax return in India?
What is the TDS rate when an NRI sells property in Mumbai?
How can an NRI repatriate money from an Indian property sale overseas?
What is the difference between NRI Taxation rules and DTAA benefits?
- Last updated:23-09-2026
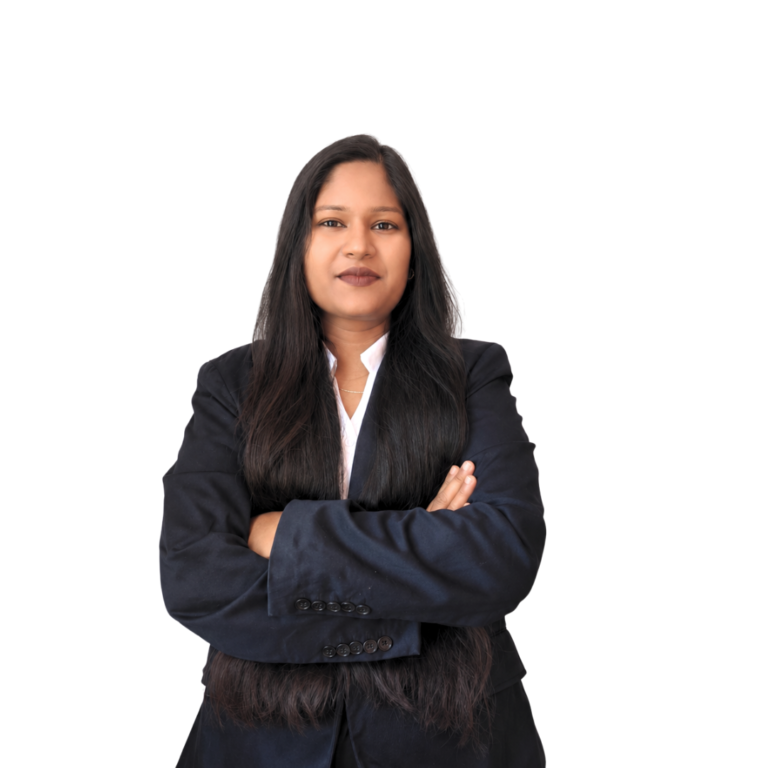
CA. Manisha Lakshkar
Manager – Direct Tax, NRI & Cross-Border Advisory
Manisha Lakshkar is a Chartered Accountant with professional expertise in Direct Tax, NRI Taxation, and Cross-Border Advisory. She advises individuals and businesses on complex Indian tax matters involving non-residents, overseas income and assets, international transactions, and cross-border financial arrangements. Her areas of professional expertise include NRI residential status determination, DTAA and treaty-based taxation, capital gains, taxation of foreign income and assets, NRI property transactions, tax implications of cross-border remittances and repatriation, and Indian tax compliance. She is experienced in addressing tax considerations arising from cross-border transactions and assisting clients with compliance requirements under applicable Indian tax laws.